Travel Debt vs. Retirement Comfort: What Are You Really Buying?
For years, I treated travel as something I could afford now and retirement as something my provident fund would handle later. But inflation, layoffs, and job uncertainty have changed that equation. How do we enjoy today without borrowing from our future?


It's 2018; travelling is as cheap as an annual Adobe subscription, and every three months, I dip into my near-empty pockets without a care in the world to see wonders beyond my city. Job safety is guaranteed, and IT careers are booming as we have never seen before.
In this article, we'll cover
- Why the old “live now, save later” approach doesn't work as well anymore
- The economic and workplace changes making both travel and financial security more expensive
- What happens when travel is funded by debt
- How I’m learning to budget for experiences without borrowing from my future
- How I calculated my own retirement number
- Why the goal isn't to choose between living today and being secure tomorrow, but to build room for both
It was a peak moment in our lives that more than half the world can no longer relate to. And a question keeps haunting me.
How do we choose between a carefree present and a comforting future as the world moves in slow motion toward dystopia?
The problem is that we can't. We can no longer make that choice because, now more than ever, a healthy present and a secure future hold equal importance. At the same time, we cannot afford to choose our previous option, which was to travel now and save later.
Travel debt has become the leading reason for personal loans in India, making up 27% of all unsecured borrowing. Thousands of young Indians are using credit cards, Buy Now, Pay Later (BNPL) platforms, and personal loans to finance "experiences" rather than traditional assets like housing or emergency funds.
One HSBC survey found that only about 33% of Indians save regularly for retirement, while a 2026 1 Finance survey found that 75.5% of middle-aged respondents lacked a detailed retirement plan.
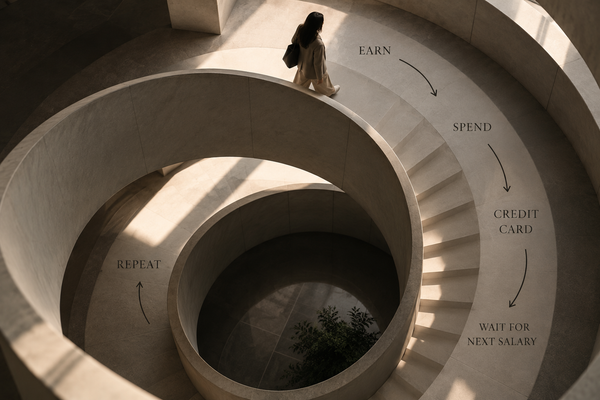
I personally used credit cards to fund half of my travel until 2024, with complete reliance on my provident fund to help me retire peacefully. I had no idea until then what inflation could do to my retirement amount, how much I really need to retire and if I even had an option to retire early.
When AI-driven layoffs began accelerating in 2025, alongside tightening visa restrictions, I knew this practice would no longer be sustainable.
I am not presenting these numbers to scare you off. This is a harsh time we are all living in, and staying delusional is not going to help anyone anymore.
It seems wrong, almost unfair, to compare the travel debt numbers everyone is accumulating and the retirement corpus that barely anyone is worried about. However, both play important roles in how we perceive being "rich" in society and define peace. We want to travel because we deserve breaks from our monotonous life or work. We also want to save enough for retirement because we want to live comfortably when we are older. Both are necessary parts of our lives, yet both seem to be mutually exclusive.
Then how do we bring in the best of both worlds into our lives?
Before we dive into what I am doing to safeguard both my present and future, we must understand why it's become harder for us to pursue either. And most of it isn't even our fault.
Everything is expensive
Inflation in India rose to 5.54% in September 2026, the highest in almost two years. After I started budgeting seriously last year, I could easily notice the difference in my grocery spending alone. Last year, my average grocery spending for two people was ~₹22K, and in 2026, it has reached ~₹25K even after cutting back on so many spending habits. The numbers are expected to increase next year as well, with no guarantee of an annual hike or job security.
Geopolitical conflicts
With back-to-back wars and conflicts raging across the world, fuel shortages and fertiliser shortages have contributed further to inflation, imbalances in demand and supply and the falling Sensex. This has created further mistrust among individuals wanting to invest in stocks but who can no longer envision the future. On top of it, travel has become infinitely more expensive in one year itself, with prices set to increase further in the coming months.
When Companies Ask More and Give Less
Has anyone noticed lately how insensitive management has become in recent years? With companies trying to create leaner teams and relying increasingly on AI, the workload on existing employees has increased significantly, on top of management issues like lack of empathy, emotional intelligence, micromanagement, refusal to provide entitled leave, among countless other issues.
Can we blame ourselves if we want to spontaneously quit and travel the world?
If you have read this far, consider supporting my work with a coffee ☕. Completely optional.
The Shrinking Safety Net of Employment
I don't even know if it's really a lack of genuine job openings or if companies have just decided to hire based on references. I have been looking for a new job for almost two years now, and I've had barely 3 interviews after applying to ~200 jobs. The job market is so bad that some of us are hiding our experience on our resumes just to get a lower-paying job or a junior role.
How are we supposed to fund our retirement plan with such an abysmal state of the job market?
What I'm Doing to Experience Both - Travel and Retirement?
For Travel
For our recent Paris trip, we spent 30% more than the amount we calculated last year. Fortunately, we had accounted for this after we noticed the increasing conflicts, sanctions and fuel shortages this year.
My husband and I have reduced our travel frequency deliberately. Since the job safety bubble is no longer the case, we wanted to ensure that we don't carry travel debt when we return from our vacation. No amount of good travel will replace the stress that's induced by the debt you accumulate and have to pay no matter what while wondering whether you can take the next trip.
Let's say you want to visit Japan for no less than two weeks. Before setting a month or a year to travel, check the flight prices for a random month ahead. Check hotel prices based on your preference and save them. Read online reviews or ask ChatGPT to research how much it would cost in Japan for travel and food every day. Make it as intensive as possible. Lastly, don't forget to add a budget for shopping.
Once you add everything up and obtain the number, add a minimum of 20% to it to get to the final number. That's the buffer against the odds.
Next is to review your finances and the month you want to travel. For example, if you want to travel after 8 months and you need to save ₹3 lakhs, it means you need to save at least ₹37,000 every single month. Have a realistic check to understand if you can truly save this amount every month without eating through your monthly expense budget and retirement savings. If not, keep pushing the months ahead until you come to a realistic figure to save.
It took us 2 years to save for the Paris trip, and it was totally worth the wait! Good things indeed take time.
For Retirement
If you are reliant on one job, your take-home salary is average, and you are not a risk taker, make additional contributions towards your provident fund, open an NPS and PPF account and contribute as much as possible.
If you earn in the higher range and you are okay with taking some risks, do the above plus invest in mutual funds or individual stocks. Markets are volatile right now, but that doesn't change my long-term approach: invest consistently, diversify appropriately and be prepared to stay invested through periods of both highs and lows.
If retirement is a priority, I'd aim to gradually get my savings rate as high as I realistically can—40% is a useful target for higher earners, but it isn't a universal rule.
Understand your retirement numbers. In order to get to this point, you need to have some idea of how much you actually spend on a monthly basis on essential versus non-essential expenses.
Assume you spend ₹1 lakh per month on essential expenses, you will retire at age 60, and your current age is 35. Also assume 6% inflation every year.
₹1,00,000 × (1.06)²⁵ = ₹4,29,187/month
So, if you spend ₹1 lakh/month today, you'd need approximately ₹4.29 lakh per month at age 60 to have equivalent purchasing power.
Now you need enough money to withdraw ₹4.29 lakh/month for 30 years.
Using a 4% withdrawal rate, I would need approximately ₹12.9 crore at age 60.
This doesn't mean I will spend only 4% of the corpus and leave the rest untouched. The 4% rule is a way of estimating the starting retirement corpus based on the annual withdrawal required.
When you understand these numbers, you will automatically realise that what you are saving is not enough. I wasted my entire 20s and initial three years of my 30s by not contributing enough to my retirement. Now, I am set to retire early at age 55, considering my salary grows at 6% every year and I still have a job.
My point is that there will always be uncertainties, and predictions could fail. However, being delusional is much more dangerous when you can actually control most of the outcomes here.
See you in the margins..